Every seller of a canal-front or Intracoastal home in Pompano Beach hands buyers a state-mandated flood disclosure at contract signing. Most buyers read it, see three checked boxes about flood damage, insurance claims and FEMA assistance, and move on feeling like the water risk conversation is closed.
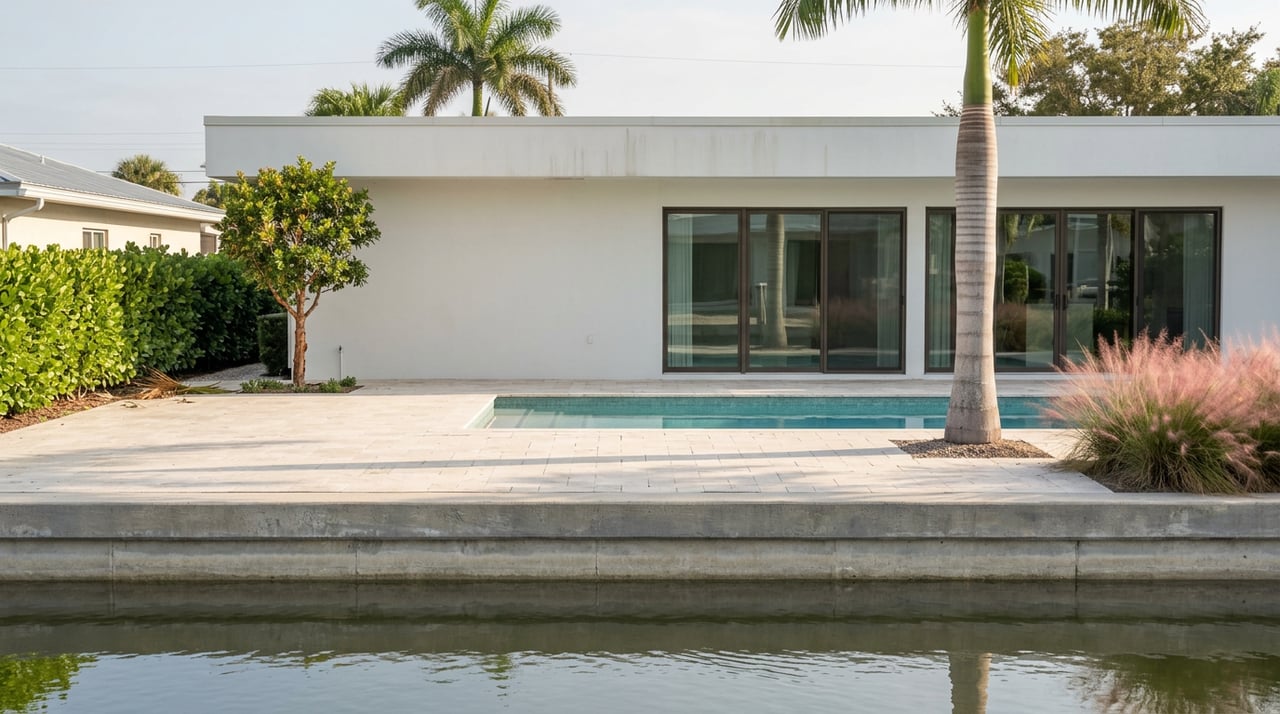
It isn't. Florida's FD-1 disclosure form, required under Section 689.302 since October 2024 and expanded again in October 2025, asks whether the seller has ever filed a flood insurance claim, received flood assistance, or knows of flood damage that occurred during their ownership. It says nothing about the seawall holding that water back in the first place. For a Harbor Village or Cypress Harbor property where the seawall is arguably the most expensive single component on the lot, that's a real gap between what the paperwork covers and what the property actually risks.
Layer a Pompano Beach city ordinance on top of that gap and the stakes get sharper. A seawall repair that looks routine on paper can legally require the entire wall to be rebuilt to current elevation code, at a cost that has nothing to do with the number on the flood form.
What the Disclosure Form Actually Covers
The FD-1 form exists to protect buyers from a narrow but real problem: sellers who know a property has flooded and stay quiet about it. It asks three questions, and only three. Has the property flooded during the seller's ownership. Has the seller filed a flood insurance claim. Has the seller received flood-related assistance from FEMA or another source.
None of those questions touch the physical condition of a seawall. A wall can be leaning, losing backfill soil behind it, or have corroded tiebacks and still produce a clean FD-1 form, because the form measures flood history, not structural integrity. Florida's older disclosure standard, the one set by the state Supreme Court in Johnson v. Davis, still requires sellers to disclose known material defects that aren't obvious to a buyer walking the property, and that duty applies even in an AS-IS sale. But "known" is the operative word. A seawall that hasn't been inspected in a decade isn't a defect anyone has "found" yet, which is exactly the gray zone where most of these deals run into trouble.
The Rule That Turns a Patch Into a Rebuild
Pompano Beach adopted its current seawall and tidal flood barrier standards in January 2022. Under City Code Chapter 151, any new or substantially repaired tidal flood barrier must sit at a minimum elevation of 5 feet NAVD88 and no higher than 5 feet 10 inches NAVD88. Broward County's parallel resiliency policy sets a slower, countywide floor: seawalls need to reach 4.0 feet NAVD88 by January 1, 2035, and 5.0 feet by 2050.
Here's the part that catches owners off guard. Pompano Beach's own standard is already tighter than the county's long-range timeline, and it applies the moment a repair crosses a specific threshold, not on some future compliance date. If the work touches more than 50 percent of the wall's shoreline length, or costs more than half of what the flood barrier itself is worth, the code treats it as a substantial repair. A substantial repair isn't a patch anymore. It's a full rebuild to current elevation standards, plus a requirement that the waterward face include lime rock riprap or another approved habitat enhancement.
So a homeowner planning to fix a 40-foot section of a 90-foot seawall, thinking it's a contained project, can find out mid-permit that the scope has just expanded to the entire wall. That's not a hypothetical. It's written into the ordinance, and it's the reason a repair estimate and a replacement estimate for the same property can be wildly far apart depending on which side of that 50 percent line the project lands on.
What the Numbers Actually Mean at Closing
Estimates published this year for South Florida seawall work put full replacement costs somewhere between roughly $800 and $1,200 per linear foot, depending on whether the wall is concrete panel, vinyl sheet pile, or another material, and how difficult the site is to access. Here's what that range looks like against typical canal lot widths in Pompano Beach's boating neighborhoods:
Canal frontage | Estimated repair range | Estimated full replacement range |
|---|---|---|
75 feet | Varies by scope | roughly $60,000 to $90,000 |
90 feet | Varies by scope | roughly $72,000 to $108,000 |
100 feet | Varies by scope | roughly $80,000 to $120,000 |
A pre-listing marine inspection, by contrast, typically runs a few hundred dollars and takes under two hours for a standard residential lot. That inspection doesn't make the seawall question disappear. It just decides who controls when the conversation happens, and on whose terms.
Older Canal Stock Makes This More Than a Theoretical Risk
Pompano Isles and the sections of Cypress Harbor closest to the Intracoastal are built on a mix of original 1960s and 1970s CBS homes alongside newer custom construction, which means a meaningful share of the seawalls behind those homes are from the same era. South Florida's coastal seawall inventory more broadly, built largely between 1955 and 1985, is aging against tide and storm-surge conditions that are measurably harsher today than when those walls went in. Concrete carbonates. Reinforcement corrodes. Tiebacks and deadmen loosen. None of it announces itself until a pool deck starts to settle or a dock piling shifts, and by then the fix is rarely small.
This is also where insurance stops helping. Standard homeowners policies in Florida commonly exclude seawalls from coverage as land improvements, and dock coverage is often restricted as well. The single most expensive structural liability on a waterfront lot is frequently the one item a homeowner's policy won't touch, which means the cost table above isn't a worst-case scenario. It's the actual out-of-pocket exposure for whoever owns the property when the wall needs work.
What Buyers and Sellers Should Actually Do
- Confirm the wall's age and material before assuming anything. A 50-year-old concrete wall carries a different risk profile than a wall replaced in the last decade, and the age alone tells you how closely to look.
- Commission a sealed engineering inspection, not just the statutory flood form. The FD-1 covers flood history. It was never designed to evaluate whether a seawall can still do its job.
- Ask what threshold any planned repair would cross. If a contractor's proposed scope touches more than half the wall's length or costs more than half its value, budget for full replacement to current elevation code, not a patch.
- Sellers should get ahead of the inspection, not behind it. Under Johnson v. Davis, a known material defect has to be disclosed even in an AS-IS contract. Finding out about a problem before listing means it can be priced into the deal on your terms. Finding out after a buyer's inspector flags it means negotiating from a number you didn't choose.
- Treat the insurance conversation as part of due diligence, not an afterthought. If a policy excludes the seawall, the replacement cost sits entirely with the owner, which changes how a buyer should think about total carrying cost before making an offer.
Single-family homes in Pompano Beach have been selling faster and with tighter inventory than they were a year ago, which means less time to sort out an engineering question once an offer is already on the table. Getting the seawall conversation started early, on either side of the transaction, isn't just good practice. It's the difference between negotiating from information and negotiating from surprise.
A Few Common Questions
Does Florida require a seawall inspection before selling a waterfront home? No. The only state-mandated document is the FD-1 flood disclosure, and it doesn't ask about the seawall's structural condition. A seawall inspection is not legally required, though lenders and insurers increasingly request one on coastal property loans.
What exactly counts as a "substantial repair" in Pompano Beach? Work that affects more than 50 percent of the wall's shoreline length, or costs more than 50 percent of the flood barrier's value along that shoreline. Crossing either line triggers full compliance with current elevation standards rather than a like-for-like repair.
Does homeowners insurance typically cover seawall replacement? Generally, no. Standard Florida homeowners policies commonly treat seawalls as land improvements and exclude them from coverage, which is why a pre-purchase inspection matters more on waterfront property than it does anywhere else in a transaction.
Waterfront property in Pompano Beach rewards buyers and sellers who ask the right question early. If you're weighing a purchase in Harbor Village, Cypress Harbor, Pompano Isles or Garden Isles, or getting ready to list a canal home anywhere along the city's waterways, Michael Miguel Gomez and the Michael Miguel Gómez team can walk you through what a specific seawall, canal, or disclosure history actually means for your deal. Schedule a free consultation before you sign anything.